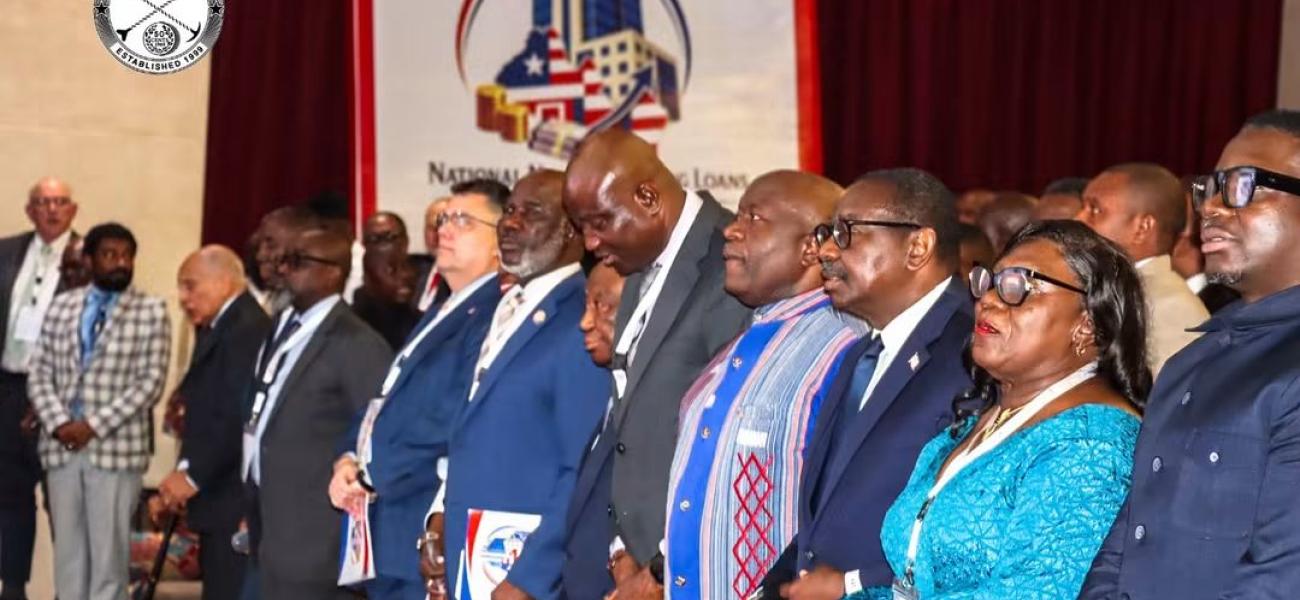
MONROVIA- Liberia has concluded a three-day National Non-Performing Loans (NPL) Resolution Conference with the adoption of a series of far-reaching resolutions aimed at reducing bad loans, strengthening the country's financial sector, and expanding access to credit for businesses and entrepreneurs.
The high-level conference, held in Monrovia from September 9–11, 2026, brought together key stakeholders from across the financial ecosystem, including the Central Bank of Liberia (CBL), commercial banks, microfinance institutions, the Ministry of Finance and Development Planning, the Ministry of Justice, the Judiciary, the Liberia Business Association, development partners, and private sector actors.
The meeting was convened against the backdrop of a growing non-performing loans challenge, which has constrained banks' ability to lend, increased the cost of credit, and limited financing opportunities for Micro, Small and Medium Enterprises (MSMEs), which are critical for job creation and economic growth.
At the end of the deliberations, participants adopted a joint communiqué containing eight major pillars of reform that are intended to improve financial stability, promote responsible lending and borrowing, and unlock greater financing opportunities for private-sector growth.
The first major resolution calls for the development of a National NPL Resolution Framework. Participants agreed that Liberia needs a comprehensive, coordinated national framework to systematically reduce existing non-performing loans while also preventing the future accumulation of distressed credit in the banking system.
The second pillar focuses on Stronger Prudential Regulation and Supervision. The conference recommended that the Central Bank of Liberia strengthen credit underwriting standards, risk management practices, loan classification, provisioning requirements, and overall supervisory oversight to ensure early detection of distressed loans.
Under this pillar, supervised financial institutions are also expected to develop measurable, time-bound plans for reducing their NPL portfolios, with clear quarterly targets that will be monitored by the CBL.
The third resolution centers on Legal and Judicial Reforms, which stakeholders identified as critical to improving credit discipline. Participants called for urgent reforms to insolvency procedures, collateral enforcement, debt recovery processes, and commercial dispute resolution.
The resolutions also strongly support the enactment of a modern Creditors and Borrowers Act, which will clearly define the rights and obligations of both lenders and borrowers and provide a more predictable legal environment for credit transactions.
The fourth major resolution addresses the long-standing issue of Government Arrears. Participants noted that delayed payments by government for bank-financed contracts have contributed significantly to the NPL problem, and therefore proposed the establishment of a Government-Bank-Contractor Resolution Mechanism.
This mechanism is expected to facilitate the timely verification and settlement of government obligations associated with bank-financed contracts, thereby restoring liquidity to contractors and improving the quality of banks' loan books.
The fifth pillar is Modernizing Credit Infrastructure. The conference recommended major improvements in credit reporting systems, collateral registries, borrower identification, and technology-driven credit assessment to reduce information asymmetry in the lending process.
Participants also proposed exploring the introduction of a Bank Verification Number (BVN) or a comparable national identification system to strengthen the credit ecosystem, reduce identity-related fraud, and enable lenders to track borrowers' credit histories more effectively.
The sixth resolution deals with Distressed Asset Resolution. Stakeholders agreed on the need for a feasibility assessment for establishing an Asset Management Company (AMC) in Liberia, alongside other market-based mechanisms, to accelerate the resolution of distressed assets and non-performing loans.
The seventh pillar emphasizes Responsible Borrowing and Credit Discipline. The resolutions call for stronger borrower accountability, improved financial literacy for both individuals and businesses, enhanced corporate governance among borrowers, and early engagement between lenders and borrowers experiencing financial distress before loans become irrecoverable.
Finally, the eighth resolution focuses on Expanding Inclusive Access to Finance. Participants called for increased responsible lending to micro, small and medium-sized enterprises (MSMEs), women-owned businesses, young entrepreneurs, and agricultural value chains that have historically been excluded from formal credit.
Consideration was also given to the use of credit guarantee schemes and other innovative financing instruments to de-risk lending to underserved sectors and encourage banks to lend more to the real economy.
A key outcome of the conference is the establishment of a National NPL Resolution Coordination and Implementation Mechanism, to be led by the Central Bank of Liberia. This body will be responsible for ensuring that the resolutions move from paper to action.
Under the communiqué, a National NPL Resolution Roadmap is expected to be developed within three months. The roadmap will outline clear responsibilities for each stakeholder, implementation timelines, performance benchmarks, and quarterly reporting mechanisms.
The resolutions are being widely viewed as an important and timely step toward strengthening Liberia's financial system, improving the quality of credit, expanding access to financing, and creating a more stable and predictable environment for private-sector investment.
Successful implementation of these measures, stakeholders say, could help restore confidence in Liberia's credit market while supporting responsible lending, sustainable business growth, and job creation across the country.